Filter posts by category

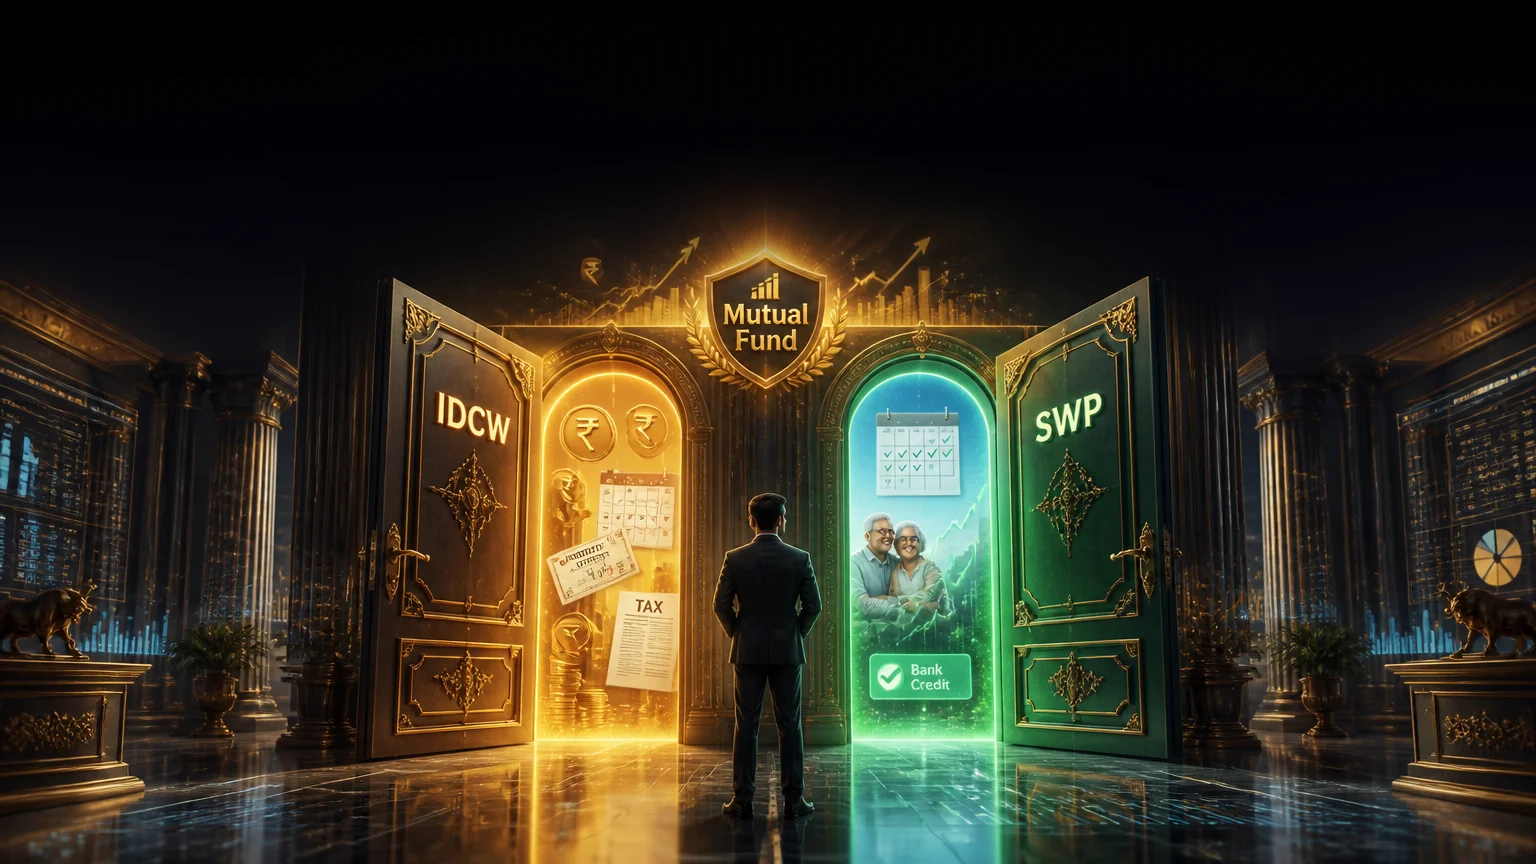
IDCW vs SWP comparison showing dividend payouts and systematic withdrawals from mutual funds for regular income planning.

IDCW vs SWP: Which Mutual Fund Income Option Is Right for You?

Quick Answer: IDCW (Income Distribution cum Capital Withdrawal) pays out fund-decided amounts taxed fully at your income slab, while SWP (Systematic Withdrawal Plan) lets you redeem a fixed amount you choose, taxing only the gain portion at capital gains rates. Both have unique benefits — IDCW can work out tax-free for households under ₹12 lakh

Healthcare after retirement

Healthcare After Retirement In short: Healthcare after retirement gets expensive fast — Indian medical costs are rising roughly 12–14% a year, well ahead of general inflation. The fix is to plan it as its own line item: keep a standalone health policy running well before you retire (don’t rely only on employer cover), size a

Retirement planning for business owners

Retirement Planning for Business Owners

Business owners in India don’t get EPF or an employer pension, so retirement planning has to be self-directed. The practical approach is: build an emergency fund first, then split retirement savings across PPF (safe, tax-free), NPS (extra tax deduction under the old regime), and mutual fund SIPs (long-term growth potential), sized to a target corpus

Indian NRI planning retirement with a financial advisor using global investments and long-term wealth management strategies

Retirement Planning for NRIs: A Step-by-Step Guide (2026)

Retirement planning for NRIs means combining NPS, mutual fund SIPs, and NRE/NRO-linked investments while staying FEMA-compliant, so your India-based corpus grows tax-efficiently and can be repatriated when you need it. As per current PFRDA and FEMA rules (2026), NRIs aged 18-70 with an NRE/NRO account can build a retirement portfolio just as resident Indians do,

Indian IT professional planning retirement with a financial advisor using SIP, NPS, and long-term investment strategies

Retirement Planning for IT Employees: A Practical Guide

Direct Answer: Retirement planning for IT employees needs a different approach than a typical salaried career, because income often peaks early, job changes are frequent, and career breaks are common. The fix is to consolidate EPF across employers, use NPS for extra tax savings, and build a dedicated equity SIP portfolio — starting in your

Disclaimer

Investments in Mutual Funds are subject to Market Risks. Read all scheme related documents carefully before investing. Mutual Fund Schemes do not assure or guarantee any returns. Past performances of any Mutual Fund Scheme may or may not be sustained in future. There is no guarantee that the investment objective of any suggested scheme shall be achieved. All existing and prospective investors are advised to check and evaluate the Exit loads and other cost structure (TER) applicable at the time of making the investment before finalizing on any investment decision for Mutual Funds schemes. Before making an investment, please contact the investment expert at Deepak Wealth Framework for designing a portfolio that suits your needs. We deal in Regular Plans only for Mutual Fund Schemes and earn a Trailing Commission on client investments. Disclosure For Commission earnings is made to clients at the time of investments. Option of Direct Plan for every Mutual Fund Scheme is available to investors offering advantage of lower expense ratio. We are not entitled to earn any commission on Direct plans. Hence we do not deal in Direct Plans.

AMFI Registered Mutual Fund Distributor | ARN - 328771 | Date of Initial Registration: 14/05/2025 | Current Validity: 13/05/2028.

Scroll to Top